
Hangarkeepers insurance is designed to help aviation businesses protect against liability for damage to aircraft owned by others while those aircraft are in the business’s care, custody or control. For fixed-base operators (FBOs), maintenance shops, flight schools, aircraft managers and hangar owners, this coverage can be an important part of a broader business insurance plan.
What is hangarkeepers insurance?
Hangarkeepers insurance, also known as hangarkeepers liability insurance, is specialized coverage designed for aviation businesses that store, maintain, repair, move or service aircraft they do not own. It helps protect against claims involving damage to non-owned aircraft while the aircraft is in the insured’s care, custody or control. While some aerospace insurance packages or aviation general liability policies may include this coverage, businesses should not assume that it is automatically provided.
Hangarkeepers insurance generally focuses on liability for non-owned aircraft that is in the insured’s care, custody or control, rather than coverage for hangar buildings, business personal property, mobile equipment or owned aircraft. Separate policies may be needed for those exposures.
Aircraft Under Care, Custody or Control vs. Third-Party Aircraft
The phrase “care, custody or control” refers to situations where an aviation business is responsible for someone else’s aircraft. That responsibility could arise during storage, repairs, fueling, towing, repositioning or other ground handling, and hangarkeepers insurance is designed to protect those handling or storing third-party aircraft from these risks.
Aircraft that are owned by the business should generally be covered through aviation hull insurance. Aircraft owners should maintain their own hull coverage as primary coverage for their plane, but depending on their business activities, they may also need hangarkeepers insurance for non-owned aircraft in their care, custody or control. It’s important to note that hangarkeepers insurance does not replace the aircraft owner’s policy, and it does not cover every aircraft-related risk.
The distinction of “care, custody or control” matters because standard general liability coverage may exclude damage to property that is under the insured’s care, custody or control. For example, if a maintenance technician damages a client’s aircraft during repairs or a line service employee causes hangar rash while moving a plane, a general liability policy may not respond unless hangarkeepers coverage is specifically included.
Types of Hangarkeepers Coverage
Hangarkeepers insurance can include several coverage components, depending on how the policy is written. The right plan should reflect the aircraft, operations, hangar structure, customer agreements and lease obligations involved.
Common coverage areas include physical damage, which helps pay for damage to customer aircraft caused by covered events like fire, vandalism or hail, and legal liability, which may help cover defense costs, settlements or judgments (up to the applicable limits) if an aviation business is sued over damage to a customer’s aircraft.
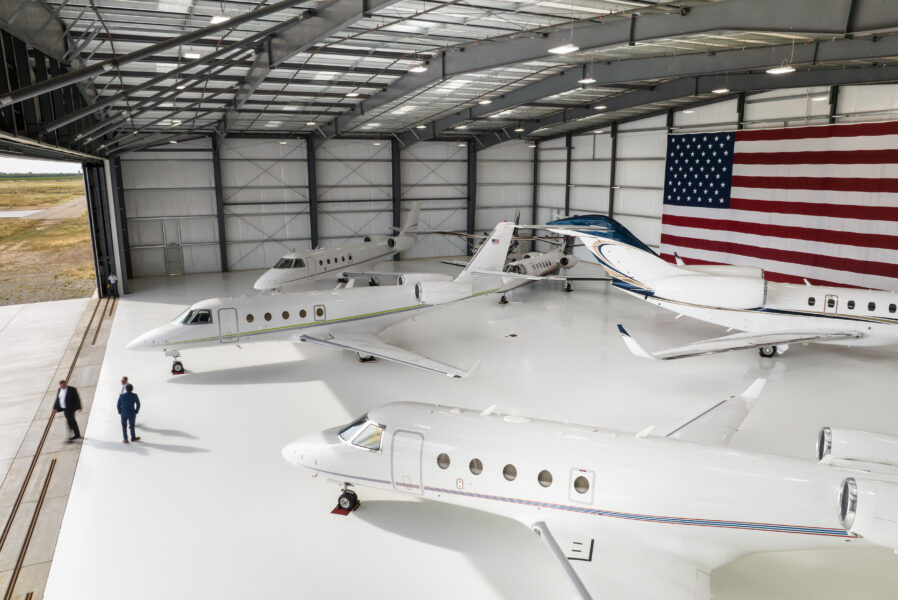
For aviation businesses, hangarkeepers coverage limits are generally based on the total or average value of all third-party aircraft in the insured’s care, custody or control. This can become especially important if one event damages several aircraft. A single fire, roof collapse or wind event can create costs that exceed expectations, especially when business jets or rare aircraft are involved.
What aviation businesses need hangarkeepers insurance?
Hangarkeepers insurance is critical for any aviation business that takes responsibility for aircraft it does not own. Businesses that commonly need this coverage include:
- Fixed-Base Operators: FBOs that provide hangar storage, fueling, tie-down services, towing or ground support may have significant exposure relating to customer aircraft.
- Maintenance, Repair and Overhaul (MRO) Businesses: MROs and maintenance shops need hangarkeepers coverage when they inspect, repair, modify or test aircraft owned by clients.
- Flight Schools: Flight training operations may have exposures involving student aircraft, rental aircraft, aircraft owned by pilots or aircraft that are stored on site for instruction.
- Aircraft Management Companies: Operators that oversee client fleets may be responsible for non-owned aircraft, even when those aircraft are parked, awaiting service or between flights.
- Charter Operators: Charter aviation businesses may store aircraft between trips and coordinate fuel, cleaning, maintenance or repositioning services.
- Avionics Shops: Businesses that install instruments, communication systems or navigation equipment are often working inside valuable aircraft that are owned by others.
- Hangar Lessors: Hangar owners and municipalities that lease space at airports may need hangarkeepers coverage.
When should a business consider hangarkeepers insurance?
An aviation business should consider hangarkeepers insurance whenever it has custody, responsibility or operational control over an aircraft owned by someone else. This situation can happen more often than many operators realize. Some common triggers include:
- Storing aircraft owned by customers, clients or third parties
- Performing maintenance, repairs, painting, avionics work or other modifications to an aircraft
- Moving, towing or positioning aircraft on behalf of owners
- Providing fueling services, cleaning or other ground support
- Accepting aircraft into a hangar, shop or ramp area under a customer agreement
- Leasing hangar space at airports that require specific insurance limits
- Entering into contracts that include indemnification, waiver of subrogation or other insurance requirements
Many airports require insurance as part of lease agreements to help address liability, property and operational risks. Customer contracts may also require specific coverage limits, additional insured status, waivers of subrogation or proof of insurance before an aircraft is stored or serviced.
Limitations and Coverage Gaps
As with any commercial insurance policy, coverage is subject to the policy’s terms, conditions, limits and exclusions. Businesses should review their insurance policies carefully before assuming a particular claim will be covered.
A single loss can damage both a hangar and the aircraft inside, making it important to understand how property, general liability, aircraft insurance and hangarkeepers coverage work together.
How to Get Hangarkeepers Insurance
Obtaining an aviation insurance package starts with understanding your operation and the value of aircraft in your care. Coverage should align with your exposures, contractual obligations and business activities, rather than price alone.
When discussing your coverage needs with your insurance advisor, consider the following:
- Aircraft Exposures: Determine the maximum value of non-owned aircraft that could be in your care at one time.
- Contracts and Requirements: Check leases, customer agreements and lender requirements for insurance obligations, limits and endorsements.
- Property Exposures: Consider hangars, tools, equipment, inventory and other assets that may require separate property coverage.
- Operational Details: Discuss factors like aircraft types, storage capacity, security measures, fire protection and claims history.
- Policy Terms: Confirm coverage limits, exclusions and how the policy applies to aircraft in your care, custody or control.
- Changes in Operation: Reassess coverage when expanding services, storing higher-value aircraft or taking on new exposures.
Insurance costs will vary based on factors such as aircraft values, coverage limits, location, operations and claims history. Private hangar owners may pay less than commercial operators or facilities that handle higher-value aircraft and more complex risks.
Personal Aircraft Owners and Hangarkeepers Insurance
While hangarkeepers insurance is typically purchased by aviation businesses, individuals who own aircraft should understand how this coverage may apply when their aircraft is stored, maintained or serviced by a third party.
An aircraft owner’s policy should still be the primary source of protection for the aircraft. If a maintenance provider, FBO or storage operator is responsible for a loss, the aircraft owner’s insurance company may seek recovery from the responsible party. Contract provisions such as waivers of subrogation can affect how these claims are handled.
Before placing an aircraft in another party’s care, owners should review insurance responsibilities and contractual requirements with their insurance advisor to better understand how a loss may be addressed.
Protecting Your Aviation Business
Hangarkeepers insurance involves complex aviation risks, specialized policy forms and important contract considerations. The right plan depends on the operation, aircraft values, location, services provided and carrier requirements.
Higginbotham’s aviation insurance specialists understand the operational exposures faced by FBOs, maintenance shops, flight schools, hangar owners, aircraft managers and other aviation businesses. Our team works with aviation clients to evaluate their risks and design tailored protection strategies that align with their goals, operations and coverage needs. To learn more about insurance options for your business, contact Higginbotham’s aviation insurance team for a consultation.